May 21, 2012
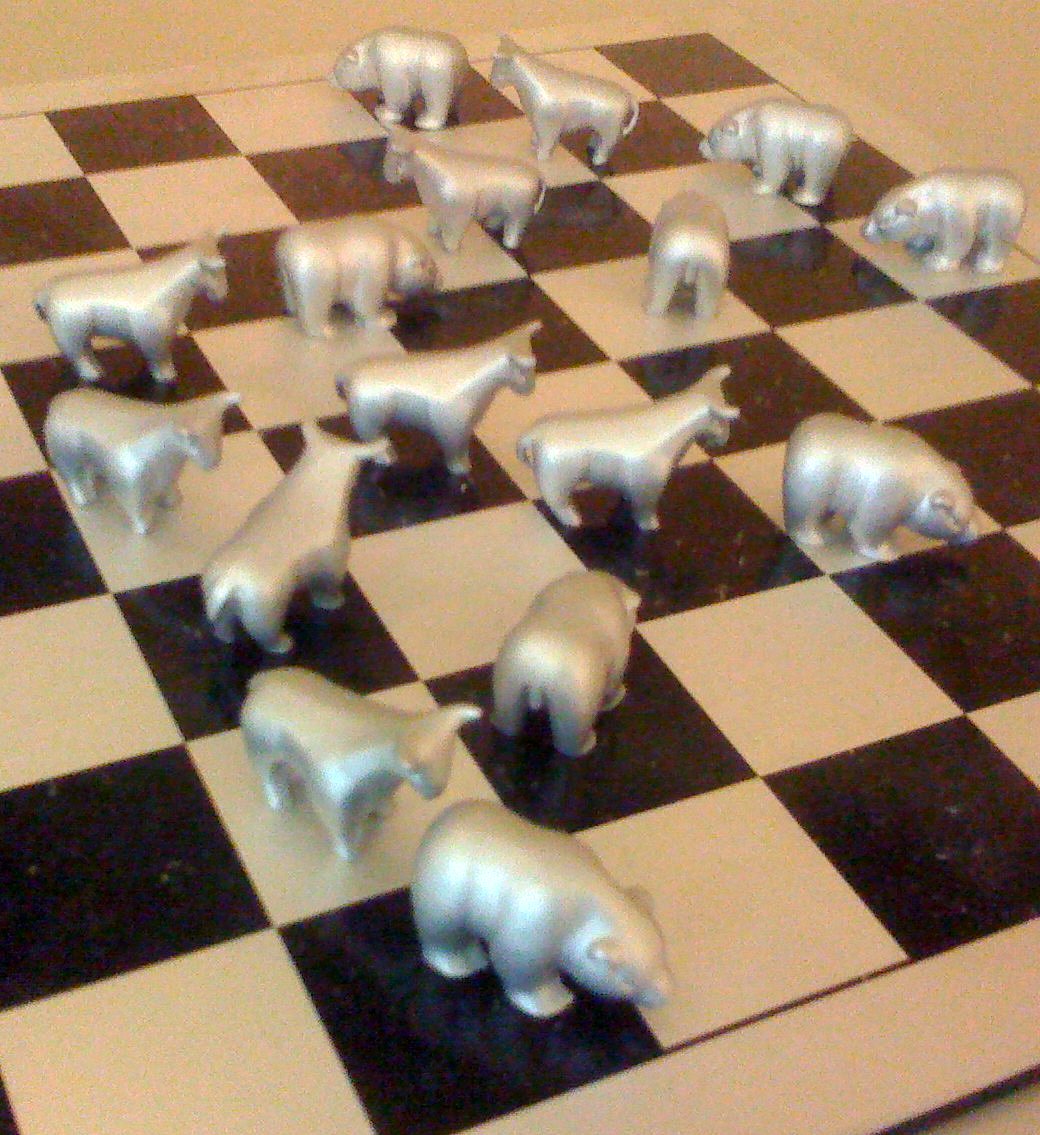
Are you a Bull or a Bear? If you are a sports fan you may think I am talking about either of the professional sports teams in Chicago, but you would be wrong! What I am actually referring to is the type of investor you are when it comes to investing in the financial markets. For those of you that don’t know, the financial markets are classed as being either a bear market or a bull market, depending on the current economic state. A bear market occurs when there is a steady decline in the stock market and investors are less confident about future prospects of stocks causing their prices to continue declining. A bull market occurs when the opposite is happening, investor optimism and confidence would be high and the stock market in general would be on an incline/resurgence with prices steadily rising.
At this current moment the world financial markets are definitely in what can be classed as a bear market, as stock prices are low and investor confidence is at an all-time low. This of course is because of the global recession that we are currently facing, which appears as If it will remain this way for the near future. Investors are really suffering because of this, as all but the sharpest and most diligent investors have pulled out of the markets and have turned to saving. This lack of confidence in the markets has spread to include prospective investors, some who have never even traded stocks before, many of them are busy looking for alternative methods of investing so than can make their money grow. The trouble with this is that the percentages currently being offered as a return on investment are so low that most end up leaving their money with their banks as the interest rates are often similar to what is being offered alternatively.
Now this is not to say that there is no money to be made in the financial markets, as there are still many investors making excellent returns daily! In fact some investors would tell you that investing now while the market is ‘bearish’ is a very smart move, which makes sense if you think about it. You see at the moment stock prices are really low and now would be the perfect time to capitalise on it. Say for instance you were looking for a long term investment; all you would have to do is research some into established companies that have relatively low stock prices, once you are satisfied that you have found the right company, purchase some of their stocks and wait. The key here is patience, as your stock might drop below the value you initially paid for it but rest assured that once we get out of this recession and the stocks start performing normally, you should make some significant profit! I can’t stress enough how important being patient is within a bear market, as the best returns can be had by keeping hold of stock that successfully makes the transition from a bear to a bull market.
This however is not the only way to make money in a bear market. A prospective investor can also start doing financial spread betting with one of the leading companies, such as Cantor Index by short selling to make profit on their investments during a bear market. This would be where you make a short term prediction/bet as to the way in which a stock/market will go, for example you can bet that a particular stock will continue falling in price and if it does you will make money however if it rises you stand to lose more than you bet initially.
Here are three tips to help you be successful in the stock market;
1. Research; The most important factor, you have to do thorough research before investing. Make sure you have sufficient knowledge of the markets before risking any of your money.
2. Split up your investments. Do not attempt to use all your investment funds to purchase one stock, as you might have predicted wrong, and your investment can become worthless quickly. Many positive returns from many small investments are better than no return from one investment.
3. Try not to sell unless necessary. Keep hold of stocks as long as you financially can whether they are performing or not. Try to set cut-off limits, so that you will have predetermined the level of profit or loss that you would be comfortable leaving the market with.
Tags:
economy,
financial planning,
money,
personal finance,
stock,
Trading
May 20, 2012
 Owning a home can be a very rewarding and fulfilling experience. Many Americans are determined to secure their finances in order to achieve their dreams and become homeowners. There are several steps prospective homeowners can take in order to make sure they are ready to make that life-changing decision.
Firstly, prospective homeowners should do research into the housing market, the location of interest, and determine what time of house and property would best suit their needs. Additionally, homeowners should determine if they are financially prepared to cover the costs of purchasing a house. Another important step before purchasing is to have a full inspection of the house. This step is expensive and can be saved for serious home buying considerations. However, there are several warning signs homeowners should keep an eye out for while they are searching for their dream home.
1. State of the Neighborhood – Potential home buyers should take a glance at the houses that surround the house of interest. They should take note of the curb appeal of other houses, the state of their upkeep, and even if there are a large number of other homes for sale nearby. It is also possible to research the amount of local crime reports in the neighborhood. It doesn’t hurt to contact the neighbors on the street to get their impressions of the neighborhood also.
2. Odor Problems – While walking through the interior and around the exterior of the house, buyers should take note of any strange odors they may come across. Smoke and pet odors are removable over time, but can take quite a bit of effort. If the house smells of mold, there is a chance of potential water damage. Additionally, if the house is covered with air fresheners, the seller may be trying to trick the buyer by covering up any lingering odors.
3. Ceiling Stains- If there are water stains on the ceiling, there is clear evidence that something may be leaking and causing water damage. This is a potential red flag for bathroom plumbing issues. The bathtub may require recaulking, pipes may need to be replaced, or the tiling may require repairs. Either way, this is a potentially expensive undertaking if it is not caught before purchasing the house.
4. Faulty Wiring- When inspecting the inside of a house, buyers should test each and every light switch and outlet to make sure they are in working order. Faulty electrical facilities can be extremely expensive to repair. Wiring problems are hazardous and can cause fires and electrocution.
5. Foundation Problems- When checking out the basement and the exterior of the house, buyers should take note of any sloping, bowing, or slanting in the ground and yard. Cracks at the base of the house are clear indicators of foundation problems and can cause water runoff to flow into the basement.
Tags:
Buyers-sellers,
financial planning,
money,
mortgage,
Property,
real estate
May 18, 2012
 Many ordinary people have recently discovered that they may not have the nest egg that they’d planned for in their retirement. Having put away regular monthly installments into investments and other savings plans, people have now discovered that these investments could be worth a lot less than they’d been led to believe. Mis sold investments are likely to cause a lot of heartache
and financial difficulty in the years to come, as people have to come to terms with the fact that they might not have sufficient money for their retirement and they could well have to rethink their plans for the forthcoming years.
With the issue of mis sold investments now coming to the fore, there is some hope for people who were given inaccurate information when they signed up to long-term investment plans. Compensation claims are being investigated and there is at least some hope of recompense for those who genuinely took out investments based on misleading information. Many people put away regular savings for their retirement, or as a means of paying off their mortgage or saving a nest egg for retirement. Without in-depth personal financial knowledge, people will have relied upon the advice offered by financial advisers, banks and other institutions in order to come to a decision about which investments to choose.
It is because this advice was – in certain circumstances – ill thought-out, or the specific investment inappropriate for the circumstances of the individual at the time, that a mis sold investment bond, or other investment product, will now come under scrutiny. It is hoped that genuine cases of mis sold investments will now be rectified to a certain extent, as individuals can make a claim for
compensation and hope to recoup their losses.
Many people will have been relying on the expected return on their investment in order to fund their retirement. The knowledge that this pot of money might no longer be available can put huge financial and emotional stress on an individual or a couple and this also needs to be taken into consideration. The situation needs to be rectified, not only on behalf of the customers who have
been mis sold investments, but also in order to ensure that financial institutions and individual advisers are seen to be held to account for any inaccurate or misleading information that they have given to customers in the past regarding the investment of their money.
With the issue of mis sold investment now out in the open, it is hoped that the message is getting through and that anyone who believes they have been misled will be able to come forward and receive more information about their investment and whether they might potentially have grounds for a claim with regards to their product. When a lifetime of savings could potentially be at stake, it’s imperative that people are now given the opportunity to check up on their finances and to have some peace of mind that their money is safe and their retirement fund will be sufficient for their needs over the years.
Tags:
Costs,
financial planning,
investments,
money,
Retirement,
Retirement Planning,
Sales
May 17, 2012
 It didn’t take long for social networking to hit the financial world in a meaningful way. No, it’s not a new app for your smartphone that lets you take a picture of a check and then deposit it into your bank account. As cool as that is, SmartyPig is at least twice as cool. Read on for proof.
What is SmartyPig?
SmartyPig (smartypig.com) is a goal-oriented internet-based savings account fully protected by the Federal Deposit Insurance Corporation (FDIC) just like the savings account at your local bank. What differentiates a SmartyPig savings account from traditional savings accounts is the unique social networking component attached to each account.
Set a goal for yourself
Aren’t all savings accounts goal-oriented? Sure, but not in the same manner as a SmartyPig savings account. When you setup a SmartyPig account you immediately identify a goal for the money. Want a new laptop computer? Make that the goal. Want to take a holiday cruise? Then that’s your goal.
After your savings goal has been identified, simply enter in the amount of your goal and the day you want to reach it.
Social Networking
What makes the SmartyPig savings accounts a zillion times more fun than a traditional savings account is that you get to share your goal with all your friends on Facebook! Just try and pretend that isn’t awesome.
But the Facebook fun doesn’t end there. Not only can your friends share in your goal by encouraging you to stay on track to achieve your goal, they can also contribute to your financial success. Just imagine 1,000 of your closest friends each contributing just one dollar each to your success. Okay, it’s probably not quite that easy, but you get the gist of how the social networking component works.
Retail Partners
Another exciting part of a SmartyPig savings account is the retailer shops that have jumped on board with cash-back savings of up to 11% on purchases, and it’s no small number of stores. Here’s a partial list:
* Amazon.com (3%)
* Banana Republic (10%)
* Gap (10%)
* Macy’s (11%)
* Old Navy (5%)
* Sports Authority (5%)
* Travelocity Hotel Gift Card (10%)
Here’s how this program works. Let’s say you have saved $1,000, reaching your goal for a vacation. When you transfer that money, as an example, to a Travelocity Hotel Gift Card you instantly get an additional 10 percent—$100 dollars—added to the gift card. That’s $1,100 to put towards your hotel. Sweet, right? Of course it is.
Interest Account
To top off everything you’ve read so far about SmartyPig savings accounts, they also pay a very competitive annual yield of 0.70% on any balance below $50,000. Accounts exceeding $50,000 earn an annual yield of 0.50%, making SmartyPig savings accounts among the most competitive in the industry.
So, what are you waiting for? Do you have a financial goal that could really get exciting with SmartyPig, your friends on Facebook, and cash back from great retail partners? Visit smartypig.com for all the details and set a plan into motion to reach your goals.
Tags:
Business,
Cash Flow,
economy,
financial planning,
money,
money savings,
savings
May 14, 2012
 When a person is in need of a large sum of money to invest in or buy an asset they borrow money or take a loan from a bank or financial institution. By doing so, the borrower is bound to pay back that sum of money to the lender in monthly on yearly installments, or part by part.
Every loan has a tenure in which the borrower has to pay back the principal amount to the lender with an added interest. These installments are to be paid on time every month or every year. An interest is a sum the borrower has to pay the lender as a cost the loan is given at. It is usually a percentage of the principal that the borrower has to pay along with the installment.
Loans are of many types the main two being secured loans and unsecured loan. Secured loans are loans in which an asset of the borrower is promised to the lender. A mortgage loan is a secured loan. An unsecured loan is a loan in which no asset of the borrower is attached. A personal loan is a kind of unsecured loan. If a borrower fails to pay one or many installments on time a default occurs. In such cases, the lender classifies your loan as a defaulted loan.
Such a status can have adverse effects on the borrowers chance to get another loan in future. If the defaulter continues this pattern of not paying his installments on time it might lower his credit rating. Financial bodies refer to these ratings to decide whether to sanction a loan to borrowers.
If the borrower fails to pay his installments, defaulted loan notifications are sent to him. These notifications are not to be ignored. The longer the borrower ignores these notifications the worse the situation gets. Non-payment of installments or the loaned amount is also a criminal offence. The financial body that lent the money may use various techniques on a borrower to pay up. Default loan harassment is the most embarrassing and irritable technique. The lender keeps calling till you pay the amount due. They send agents to show up at your house and harass your family. The lender might also usurp the asset attached or mortgaged in case of secured loans. Once the asset is taken in there is no way to get it back but to repay the loan amount.
Tags:
budgeting,
College Loans,
Education Loans,
financial planning,
loans,
money,
students Loans


 admin •
 5:20 am •


Recent Comments